Welcome to our public Country-by-Country Reporting resource hub
Updated: September 2026
Here we set out why and how multinational business should embrace tax transparency, together with the very latest news and analysis.
Public Country-by-Country Reporting (pCbCR) of tax information by multinational enterprises (MNEs) is the hottest topic in financial reporting right now.
Driven by legislative developments in Europe and Australia, and accounting developments in the United States, the year 2026 will be a breakthrough year for corporate pCbCR. There will be a cascade of corporate tax transparency from thousands of businesses in connection with financial year 2025. The focus is very much on corporate income tax, as explained in Why corporate income tax is the most critical of all taxes.
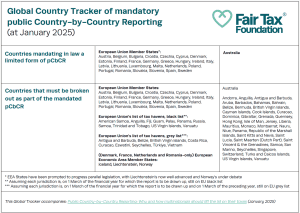
The EU pCbCR Directive requires large MNEs that have a substantial presence in Europe to publicly share key financial information on their operations in each EU Member State and a designated list of tax havens.
Early adoption of EU legislation in Romania, Croatia, Hungary and Spain has even seen large businesses with a substantial presence in these countries, and which have an ultimate parent entity outside the EU, needing to take action from as early as 2025. Multinationals based in the likes of the United States, the United Kingdom, Japan and Switzerland have become the first wave of corporate income tax pCbCR pioneers. In 2026, Spain’s shortened filing deadline (reports required within six months of the balance sheet date) has driven an increase in first reports from Spanish MNEs with financial years ending on 31 December 2025.
We have been tracking the first wave of tax transparency reports to emerge as a consequence of the EU pCbCR Directive, and publishing regular analysis of our findings. As at end September 2026, we have tracked, analysed and rated 741 pCbCR reports from 650 MNEs. The most significant proportion of the 650 MNEs analysed and rated below connect to filings in Spain (276). Followed by Romania (201), Ireland (28) and Croatia (24). Many MNEs are now on the second year of their reporting in connection with Romania. Some MNEs are lodging pCbCR filings in more than one country (e.g., a combination of Romania and Spain, or Romania and Croatia).
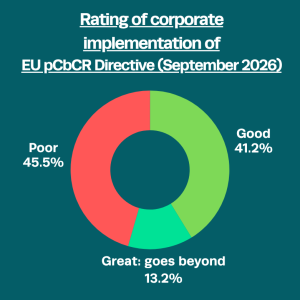
More than half (54%) of the pCbCR reports produced by these 650 large multinationals in connection with the EU pCbCR Directive are good, solid attempts to be open and honest. A significant minority (13%) went much further than required by the Directive.
However, in 46% of instances reporting is poor: with 40% of MNEs disclosing data on economic activity in relation to the country of filing only (e.g., Romania only); 2% of MNEs breaking down activity in connection with the EU’s tax havens lists only (e.g., Panama, Russia and the British Virgin Islands); and 3% omitting some or all datasets (e.g., data on profits is missing).
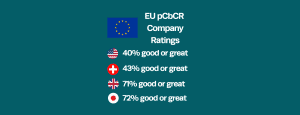
There are wide national variances. The frequency of good application of the EU pCbCR requirements was substantially above average among business headquartered in Spain (at 89%) and Japan (69%), and substantially below average among business headquartered in the US (37%) and Switzerland (38%). While MNEs with an ultimate incorporation on the UK mainland applied the requirements well with greater frequency than average (60%), those with an ultimate parent entity in UK overseas territories (such as the Cayman Islands) or UK crown dependencies (such as Jersey) are emerging as laggards – with the tax transparency displayed by such businesses among the very worst (at 32%).
Many MNEs have now produced more than one filing in connection with earliest adopting EU Member States. We have analysed 91 of these subsequent reports published by the same MNEs. These largely fall into two categories: reports covering a subsequent financial year; and revised reports that replace an earlier report for the same financial year. To date, only a handful of companies show a tendency to improve in filings following their first attempt.
At the bottom of this page you will find our running macro-assessment of the raw numbers (as at end September 2026): broken down by sector and country of ultimate incorporation.
Paul Monaghan, Fair Tax Foundation Chief Executive commented:
“There is much to celebrate in our findings, but also causes for concern. The majority of multinationals that are impacted by the EU pCbCR Directive have implemented these new tax transparency rules with integrity and courage. Some have even taken the opportunity to go much further, and extend their reporting to all countries in which they operate and to other taxes. Others have opted to implement the directive earlier than required.
“On the other hand, many businesses, especially those based in the United States and Switzerland, have opted to do little or nothing. This is regrettable, not least as robust implementation of the EU pCbCR is sure to become a prominent key performance indicator of responsible tax conduct among investors and other stakeholders.”
Institutional investors, asset managers and ratings agencies are salivating at the prospect of accessing such data for the first time and being able to form a more rounded view of company tax conduct. While firms engaging in higher levels of tax avoidance tend to be averse to disclosing CbC information, research has found that investors are rewarding increased transparency and tax-responsible behaviour via a lowering of the cost of equity capital.
The legislative and accounting developments are far from perfect, but they will raise the tax transparency bar considerably and serve as an embarkment point for those multinationals who rightly decide that they may as well go ‘all in’ and embrace full and complete pCbCR, as championed by the Fair Tax Mark.
Where mandatory pCbCR has already been introduced (e.g., in connection with large European banks and extractive industries), there is evidence of reduced use of tax havens, reduced profit shifting, increased effective tax rates and increased domestic tax revenue mobilisation.
Mandatory pCbCR would enable low- and lower middle-income countries to have access to large multinationals’ CbCR data for the first time – given the majority of these countries are currently locked out of global confidential information sharing systems.
Businesses that are Fair Tax Mark accredited are well placed to transition painlessly to a world where a step change in tax transparency is increasingly an expected, if not a mandatory requirement.